Roof Insurance Claims
After a Storm, Your Insurer Needs Proof of the Damage
The wind dies down. You walk outside and see shingles scattered across your lawn. Part of your roof is exposed. You call your insurance company, and they tell you to get a contractor estimate. You're stressed, your home is exposed to weather, and now you're trying to manage an insurance claim on top of everything else. Roof insurance claims feel overwhelming because they are. Greenville Roofing Solutions handles the documentation, communication, and coordination with your insurer so you're not managing this alone. We photograph damage, provide detailed estimates, and work with adjusters to get your roof repaired.
How Insurance Coverage Works
Your homeowner's insurance covers damage from storms, falling trees, and sudden events. It doesn't cover damage from neglect, age, or poor maintenance. It covers the cost of repair, or replacement if damage is too extensive to repair cost-effectively. It comes with a deductible you pay out of pocket. Most people are surprised by how much documentation and coordination their claim requires.
Our Role in Your Claim
We respond quickly after a storm and photograph damage immediately. Fresh damage is easier to document and more convincing to insurers than damage assessed weeks later. We provide detailed written estimates that your insurer can review. We explain what caused the damage and what work is needed. We answer questions from insurance adjusters. We coordinate with their timeline so the claim process moves forward.
Sometimes we discover that damage is more extensive than initially apparent. We communicate that to you and your insurer. We document everything so there are no surprises later.
Filing the Claim
You typically initiate the claim by calling your insurance company and reporting the damage. They schedule an adjuster to inspect. You can have us present during the inspection to answer technical questions and ensure the adjuster sees all the damage. The adjuster determines what's covered and what your payout will be. You receive a check and can authorize repairs.
If your insurer's estimate differs from ours, we can discuss the discrepancy and provide evidence supporting our assessment. Most disagreements resolve quickly when both estimates are detailed and professional.
Timing Matters
File your claim soon after damage occurs. Delays give insurers reasons to question whether damage was recent or pre-existing. We help close that gap by responding fast and providing immediate documentation.
Temporary Protection While Claims Process
If weather is ongoing or the damage is severe, we can install temporary tarping or boarding to protect your home while the claim processes. This is important if the claim takes weeks to settle. You don't want water intrusion continuing while paperwork gets handled.
Coverage Limits and Deductibles
Your policy has a limit on how much the insurer will pay for roof damage. It has a deductible you pay. Some policies cover replacement cost. Others cover actual cash value (depreciated value). Older roofs may have lower coverage limits. We help you understand what your policy covers and what your out-of-pocket responsibility is.
When Insurers Deny Claims
Occasionally insurers deny claims or offer less than expected. If they claim damage is pre-existing, we can provide evidence that it's recent. If they claim poor maintenance caused failure, we can explain how the damage resulted from the storm event. We work with you to contest denials and push for fair coverage.
Age and Your Roof
Insurers sometimes use roof age as a reason to deny coverage or offer reduced payouts. A roof that's 20 years old may be considered near the end of its life. Damage to a 20-year-old roof may result in depreciated value rather than full replacement cost. We explain these policies and help you understand what's reasonable to expect.
Planning for Replacement
Sometimes a storm triggers replacement rather than repair. The damage is too extensive, or the roof is old enough that replacement makes more sense than patching. Insurance may cover full replacement cost if the damage is severe enough. We help evaluate whether repair or replacement is the right path.
Why Homeowners Trust Us With Claims
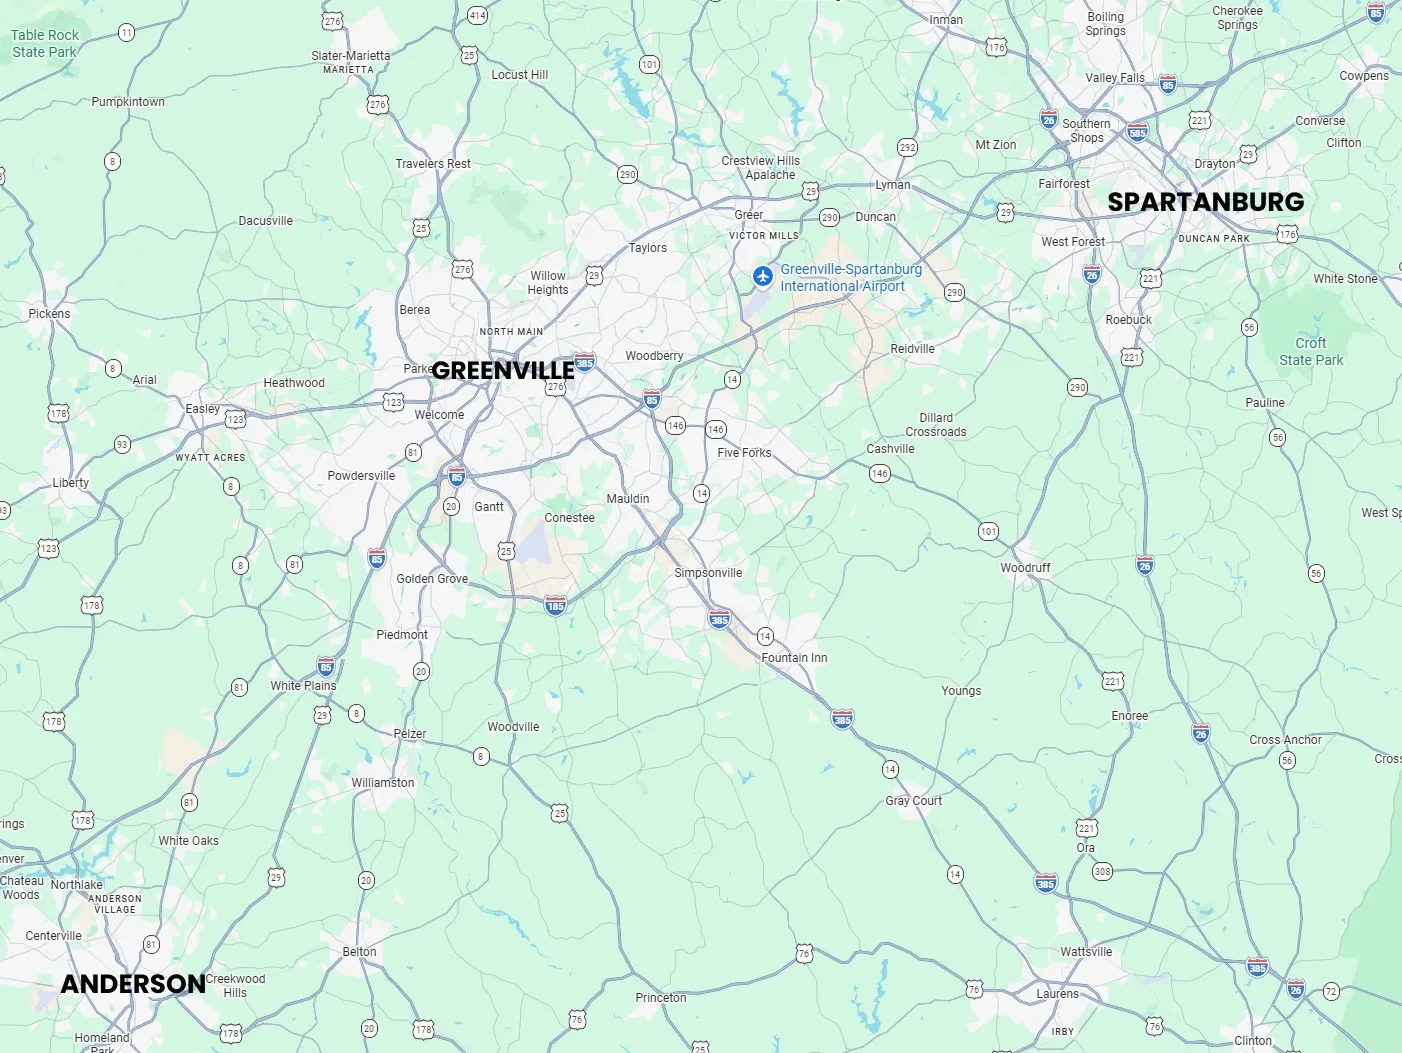
We understand the insurance process and advocate for fair coverage without being unreasonable with insurers. We document thoroughly so claims move forward efficiently. We communicate clearly so you understand what's happening at each step. We serve Greenville County, Anderson County, and Spartanburg County with the same experience and integrity.
After a Storm, Call Immediately
If your roof is damaged, call us right away. We'll dispatch a crew to assess and protect your home from further weather damage. We'll photograph everything and start the documentation your insurance claim needs.
Call 864-365-2955 for emergency response to storm damage.
Our Services
Whether your roof needs an emergency repair, a full replacement, or preventive maintenance, Greenville Roofing Solutions handles residential and commercial projects across Upstate South Carolina. We're here when you need us most.
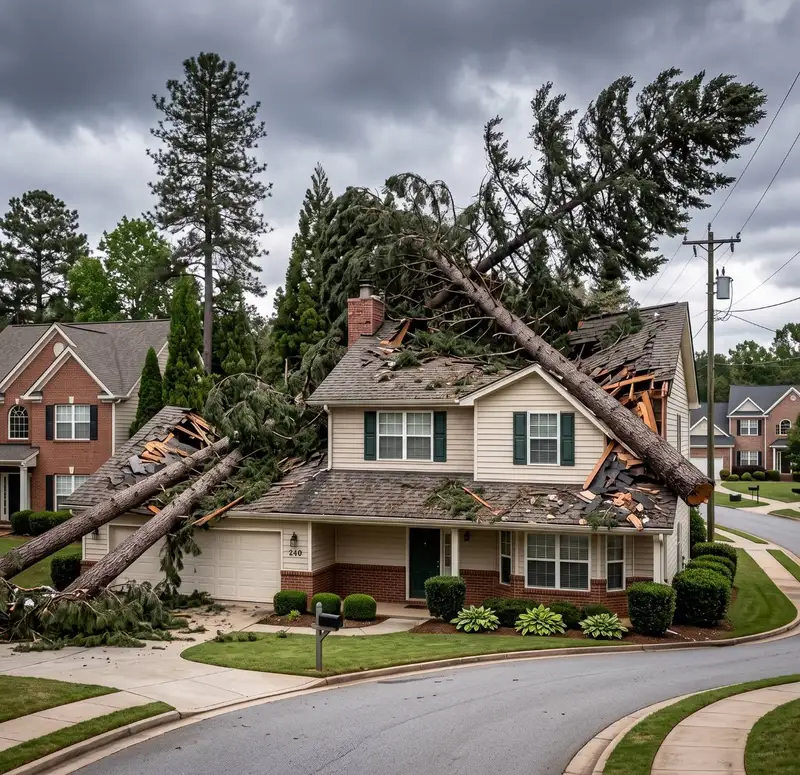
Emergency Roof Repair
Leaks, storm damage, or missing shingles. We respond fast to stop water intrusion and protect your home.
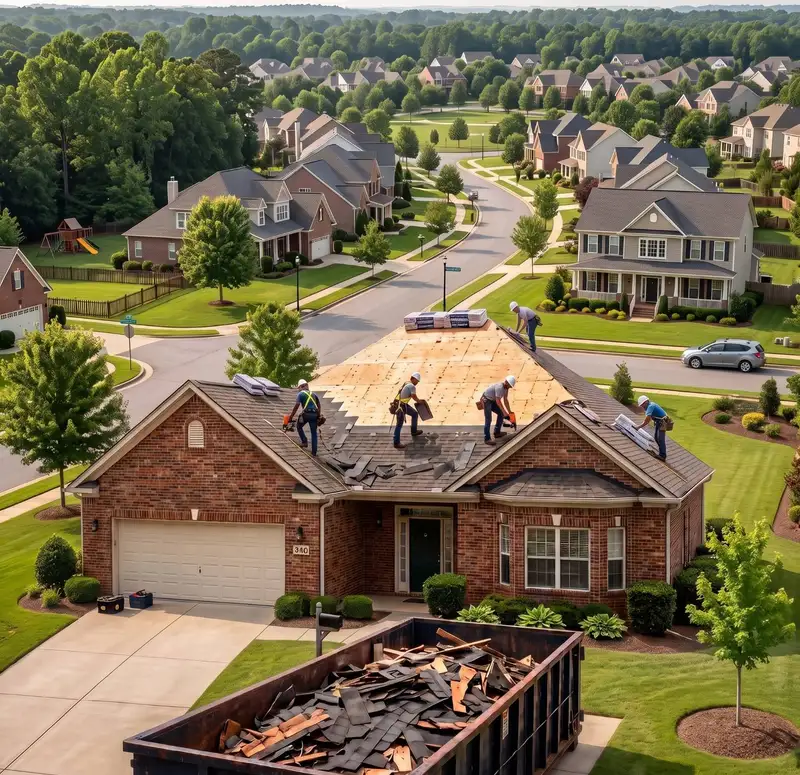
Roof Replacement
When repair won't cut it, we install a new roof built to last and protect your home for decades.
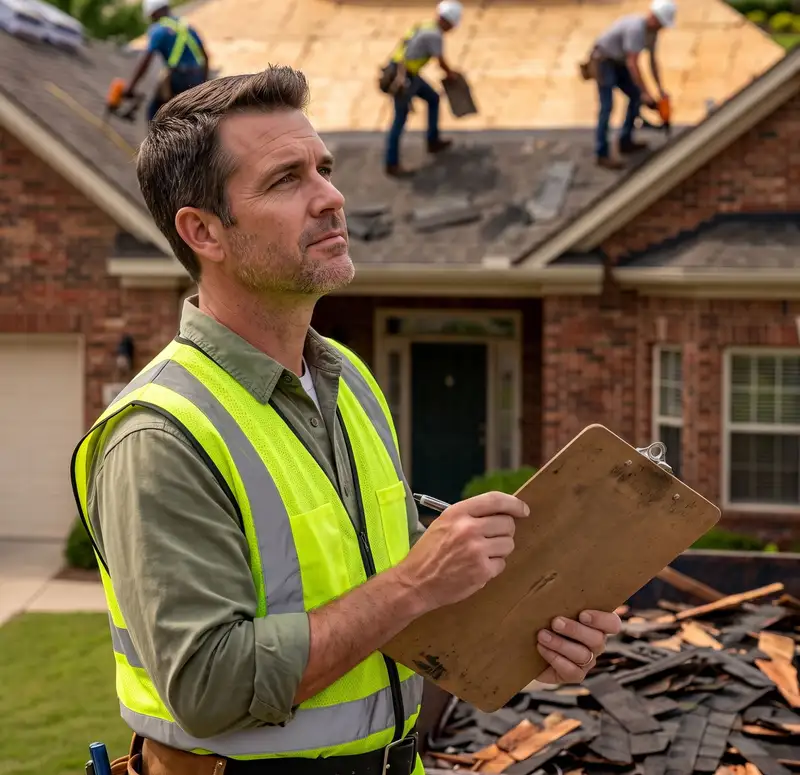
Roof Insurance Claims
Storm damage? We document the loss, work with your insurer, and handle the repairs.
Commercial Metal Roofing
Metal roofing delivers durability, energy efficiency, and decades of protection for your building.
Commercial Roof Coatings
Extend your roof's life and cut cooling costs with a commercial-grade protective coating system.
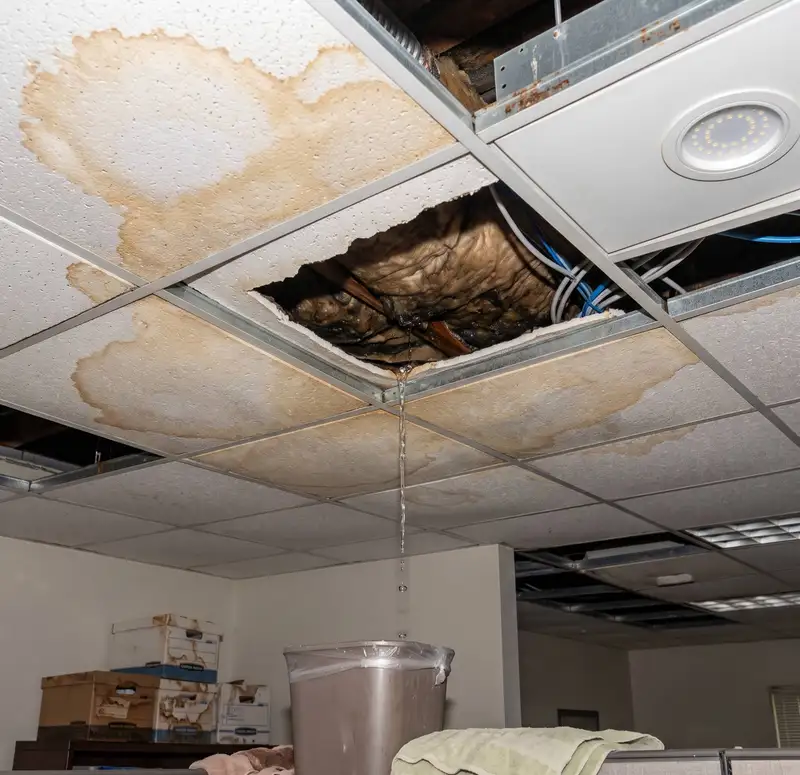
Emergency Commercial Roofing
Storm damage, leaks during business hours, or roof failure. We respond to keep your operation running.
Serving Greenville, Anderson & Spartanburg Counties
Ready to talk roofing?
Call us or fill out the form to request a free estimate. One of our team members will get back to you soon.